The Sharpe Ratio is a measure of the risk-adjusted return of an investment.
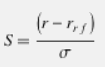
- r = average monthly return
- rrf = risk-free return (by default, we use 0% per year for all time periods)
- σ = standard deviation of the monthly returns over the same period
For the annualized Sharpe Ratio, the monthly Sharpe Ratio is multiplied by the square root of 12.
The Sharpe Ratio can be calculated on a daily, monthly, or quarterly basis, or over different periods such as 3 or 6 months, or 1–10 years.
Available risk-free return rates
The ratio can be calculated using the following risk-free return rates:
- Sharpe Ratio 0% (default)
- Sharpe Ratio 1%
- Sharpe Ratio 1.5%
- Sharpe Ratio (3-Month T-Bill)
- Sharpe Ratio (10-Year T-Note)
- Sharpe Ratio (30-Year T-Bond)